

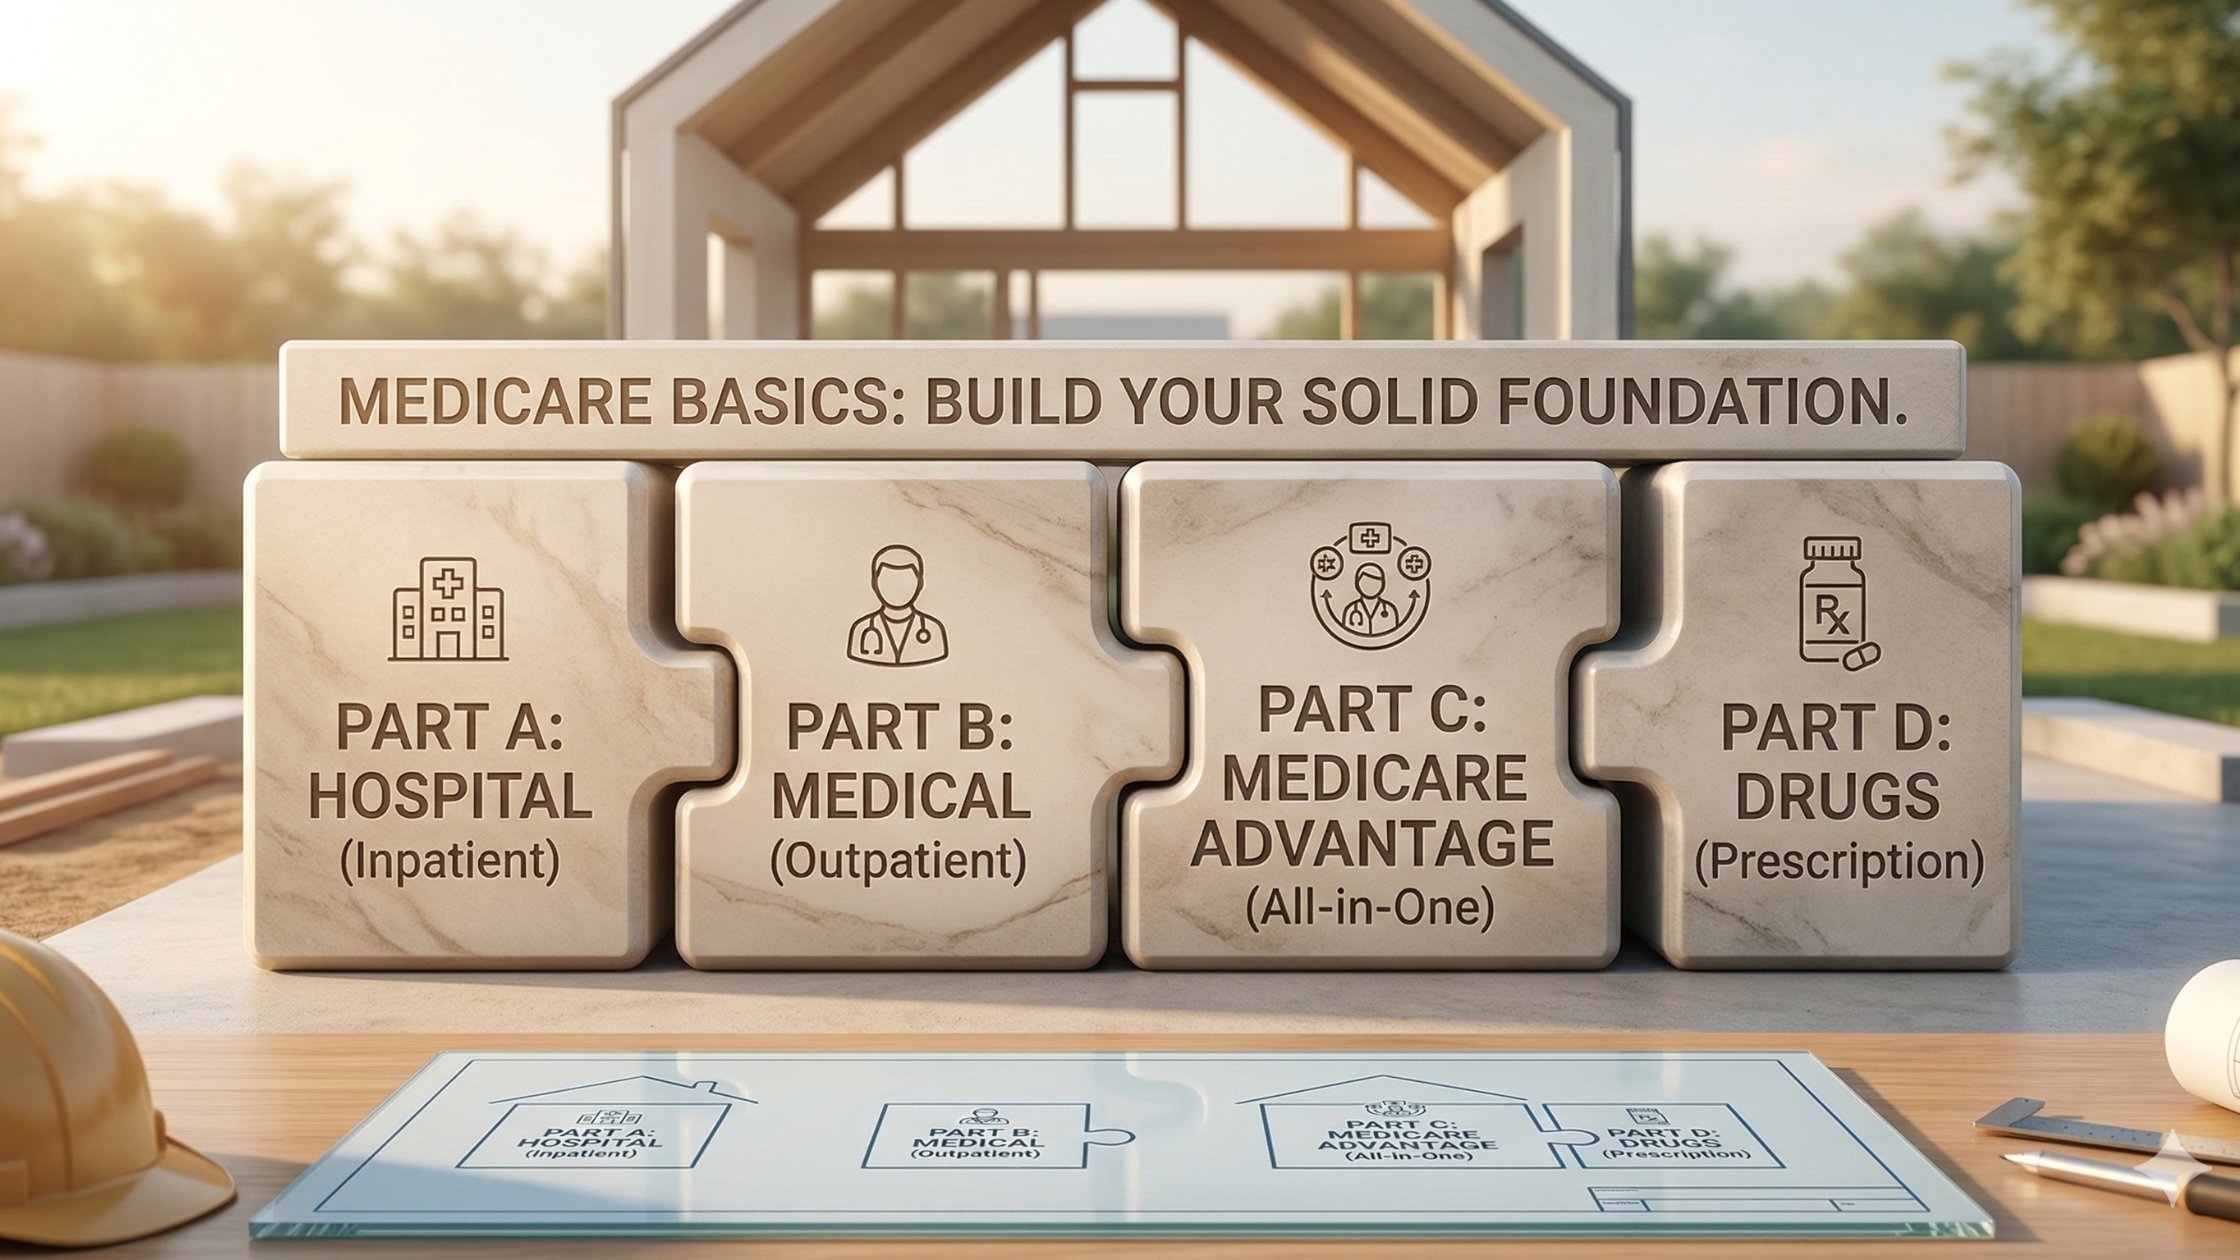
Imagine you are building a brand new house from the ground up. Before you can pick out the paint colors or the roof tiles, you need a rock solid foundation. Navigating your healthcare options as you approach age 65 feels a lot like building that house.
Therefore, you need to understand the foundation before adding the extra features. That is exactly why mastering Medicare Basics for beginners is so vital. Ultimately, this knowledge sets up your health and finances for a secure future.
Right now, nearly 69.7 million Americans rely on this program for their healthcare needs.
Why are Medicare Basics for beginners so important?
Many people find the transition to Medicare overwhelming and confusing. For instance, there are deadlines, penalties, and a whole new alphabet of parts to learn. Without clear guidance, it is very easy to make costly mistakes.
Consequently, learning the fundamentals gives you peace of mind. You want to make choices that protect your health and your life savings. We understand that you value clarity and expert support during this transition.
As a result, getting the right information today means you can relax and enjoy your retirement tomorrow.
What are the different parts of Medicare?
First, the system is divided into four main parts. Each part covers a specific type of healthcare service. Furthermore, it helps to look at them side by side to avoid confusion.
Here is a simple table to break down the alphabet soup of coverage.
| Medicare Part | What It Is | What It Covers |
| Part A | Hospital Insurance | Inpatient hospital stays, skilled nursing facility care, hospice care, and some home healthcare. |
| Part B | Medical Insurance | Doctor visits, outpatient care, medical supplies, and preventive services. |
| Part C | Medicare Advantage | An alternative to Original Medicare offered by private companies. It bundles Part A, Part B, and usually Part D. |
| Part D | Prescription Drug Coverage | Helps cover the cost of prescription medications. |
What does Original Medicare cover?
Original Medicare consists of just Part A and Part B. Specifically, the federal government manages this program directly. As a result, it covers a large portion of your hospital and medical expenses.
However, Original Medicare does not cover everything. In fact, it typically pays about 80 percent of your approved medical costs. Therefore, you are responsible for the remaining 20 percent.
Additionally, this basic program does not include prescription drug coverage.
How does Medicare Advantage work?
Medicare Advantage is also known as Part C. Private insurance companies approved by the government offer these plans. In recent years, over 51 percent of eligible beneficiaries have chosen Medicare Advantage plans for their coverage (KFF.org).
To put it simply, these plans bundle your hospital and medical coverage into one single plan. Furthermore, most also include prescription drug coverage. In addition, some plans even offer extra benefits like dental, vision, or fitness club memberships.
When do I need to sign up for Part B?
Your Initial Enrollment Period is a very important window of time. Generally, it lasts for seven months total. Specifically, the timeframe begins three months before your 65th birthday month.
Then, the window includes your birthday month and ends three months later. If you are already receiving Social Security benefits, you will likely be enrolled automatically. Otherwise, you must actively sign up to avoid late penalties.
What if I am still working at age 65?
If you or your spouse are still actively working, you might have group health insurance. In that case, if the employer has 20 or more employees, your group plan usually pays first. Because of this, you can safely delay Part B enrollment.
Later, once you retire or lose that employer coverage, you will get a Special Enrollment Period. Consequently, this period lasts for eight months. Most importantly, it allows you to sign up for Part B without any late penalties.
Finally, it is critical to get written proof of your creditable coverage from your employer.
How much does Medicare cost?
A common misconception is that this healthcare program is entirely free. Even though you have paid into the system through taxes, there are still monthly costs. Ultimately, your specific costs will depend on the choices you make.
Will I pay a premium for Part A?
Most people do not pay a monthly premium for Part A. Thankfully, you get it premium free if you or your spouse worked and paid Medicare taxes for at least 10 years. Basically, those 10 years equal 40 quarters of employment.
On the other hand, if you do not meet this work history requirement, you can still buy Part A. Consequently, you will just have to pay a monthly premium for it.
What is the standard Part B premium?
Almost everyone pays a monthly premium for Part B. Each year, the government sets a standard premium amount. Generally, this premium is deducted directly from your Social Security check.
However, higher income earners might have to pay more for Part B. Specifically, this extra charge is known as the Income Related Monthly Adjustment Amount. Moreover, it is based on your tax returns from two years prior.
What is the difference between Medigap and Medicare Advantage?
You have two main paths to choose from when finalizing your coverage. First, you can stick with Original Medicare and add a Medigap policy. Alternatively, you can choose a Medicare Advantage plan.
Medigap policies are Medicare Supplement Insurance plans. Basically, they help pay the 20 percent gap that Original Medicare leaves behind. Although you will pay a higher monthly premium, you will have very few out of pocket costs when you see a doctor.
Why might someone choose Medigap?
Medigap offers incredible freedom of choice. For instance, you can see any doctor or visit any hospital in the United States that accepts Original Medicare. Furthermore, you do not need referrals to see specialists.
Undoubtedly, this predictability is very appealing. As a result, you know exactly what your healthcare costs will be each month. For people who travel often or have complex medical needs, this peace of mind is invaluable.
Why might someone choose Medicare Advantage?
Medicare Advantage plans appeal to those who prefer an all in one approach. For example, they enjoy having a single ID card for medical, hospital, and pharmacy benefits. In addition, the extra perks, like vision and dental coverage, are also a major draw.
Often, these plans have a zero dollar monthly premium. Nevertheless, you must carefully check the network of doctors. Specifically, if you go outside the plan network, your care might not be covered at all.
Do I really need prescription drug coverage?
Yes, it is highly recommended to get Part D coverage. Even if you do not take any medications right now, your health needs can change. Consequently, enrollment in prescription drug plans continues to grow to cover daily medication needs for millions of people (Medicare.gov).
Unfortunately, if you go without creditable drug coverage for 63 days or more, you could face a permanent late enrollment penalty. Fortunately, you can get this coverage through a standalone Part D plan. Similarly, you can also get it bundled inside a Medicare Advantage plan.
How does the Part D penalty work?
First of all, the Part D penalty is not a one time fee. Instead, it is a permanent extra charge added to your monthly premium. Furthermore, the penalty amount is calculated based on how many months you went without coverage.
Sadly, this extra cost stays with you for as long as you have a Part D plan. For that reason, we strongly suggest enrolling in a drug plan as soon as you are eligible. Even a low cost plan protects you from future penalties.
How can The Medicare Coach help me?
Navigating this system alone can feel like learning a foreign language. In fact, the rules change constantly, and the sheer volume of mail you receive is overwhelming. That is exactly where our experience and trust make all the difference.
For anyone looking to enroll into Medicare for the first time, our team is here to guide you. Specifically, we provide personalized, expert support through Our Medicare Enrollment Concierge services. As a result, we help you compare your options and choose the exact right plan for your unique needs.
At The Medicare Coach, our goal is to simplify this entire process for you. Therefore, we take the stress out of your transition so you can focus on enjoying your life. Ultimately, you deserve to feel fully confident in your healthcare decisions.
What are the most common mistakes to avoid?
Without a doubt, the biggest mistake people make is missing their Initial Enrollment Period. Consequently, missing this window can result in lifetime financial penalties. Furthermore, it can delay your health coverage when you need it most.
Another mistake is assuming your spouse has the same needs as you. Generally speaking, healthcare is highly individual. Therefore, a plan that works perfectly for your neighbor or your spouse might be terrible for you.
Additionally, another frequent error involves Health Savings Accounts. Specifically, if you are drawing Social Security benefits, your Part A enrollment is automatic. However, once you have Part A, you can no longer contribute funds to a Health Savings Account.
If you continue contributing, you could face tax penalties from the IRS. Therefore, it is essential to stop all contributions at least six months before you apply for Medicare. Ultimately, this rule catches many working adults by surprise.
Finally, many people fail to review their coverage every year. For instance, plans change their pricing and their covered medications annually. Consequently, staying informed ensures you are never caught off guard by sudden medical bills.
Conclusion
In conclusion, learning how this system works does not have to be a frustrating experience. By understanding the four parts of coverage and knowing your enrollment timelines, you are already ahead of the game. Most importantly, a solid foundation of knowledge protects you from penalties and poor coverage choices.
Always remember that you do not have to make these big decisions alone. In fact, getting expert advice ensures you select the perfect plan for your lifestyle and budget. Ultimately, understanding these Medicare Basics for beginners is your first step toward true peace of mind.
Are you ready to take control of your healthcare future and explore your options today?
