

Key Takeaways How Medicare Works When Traveling:
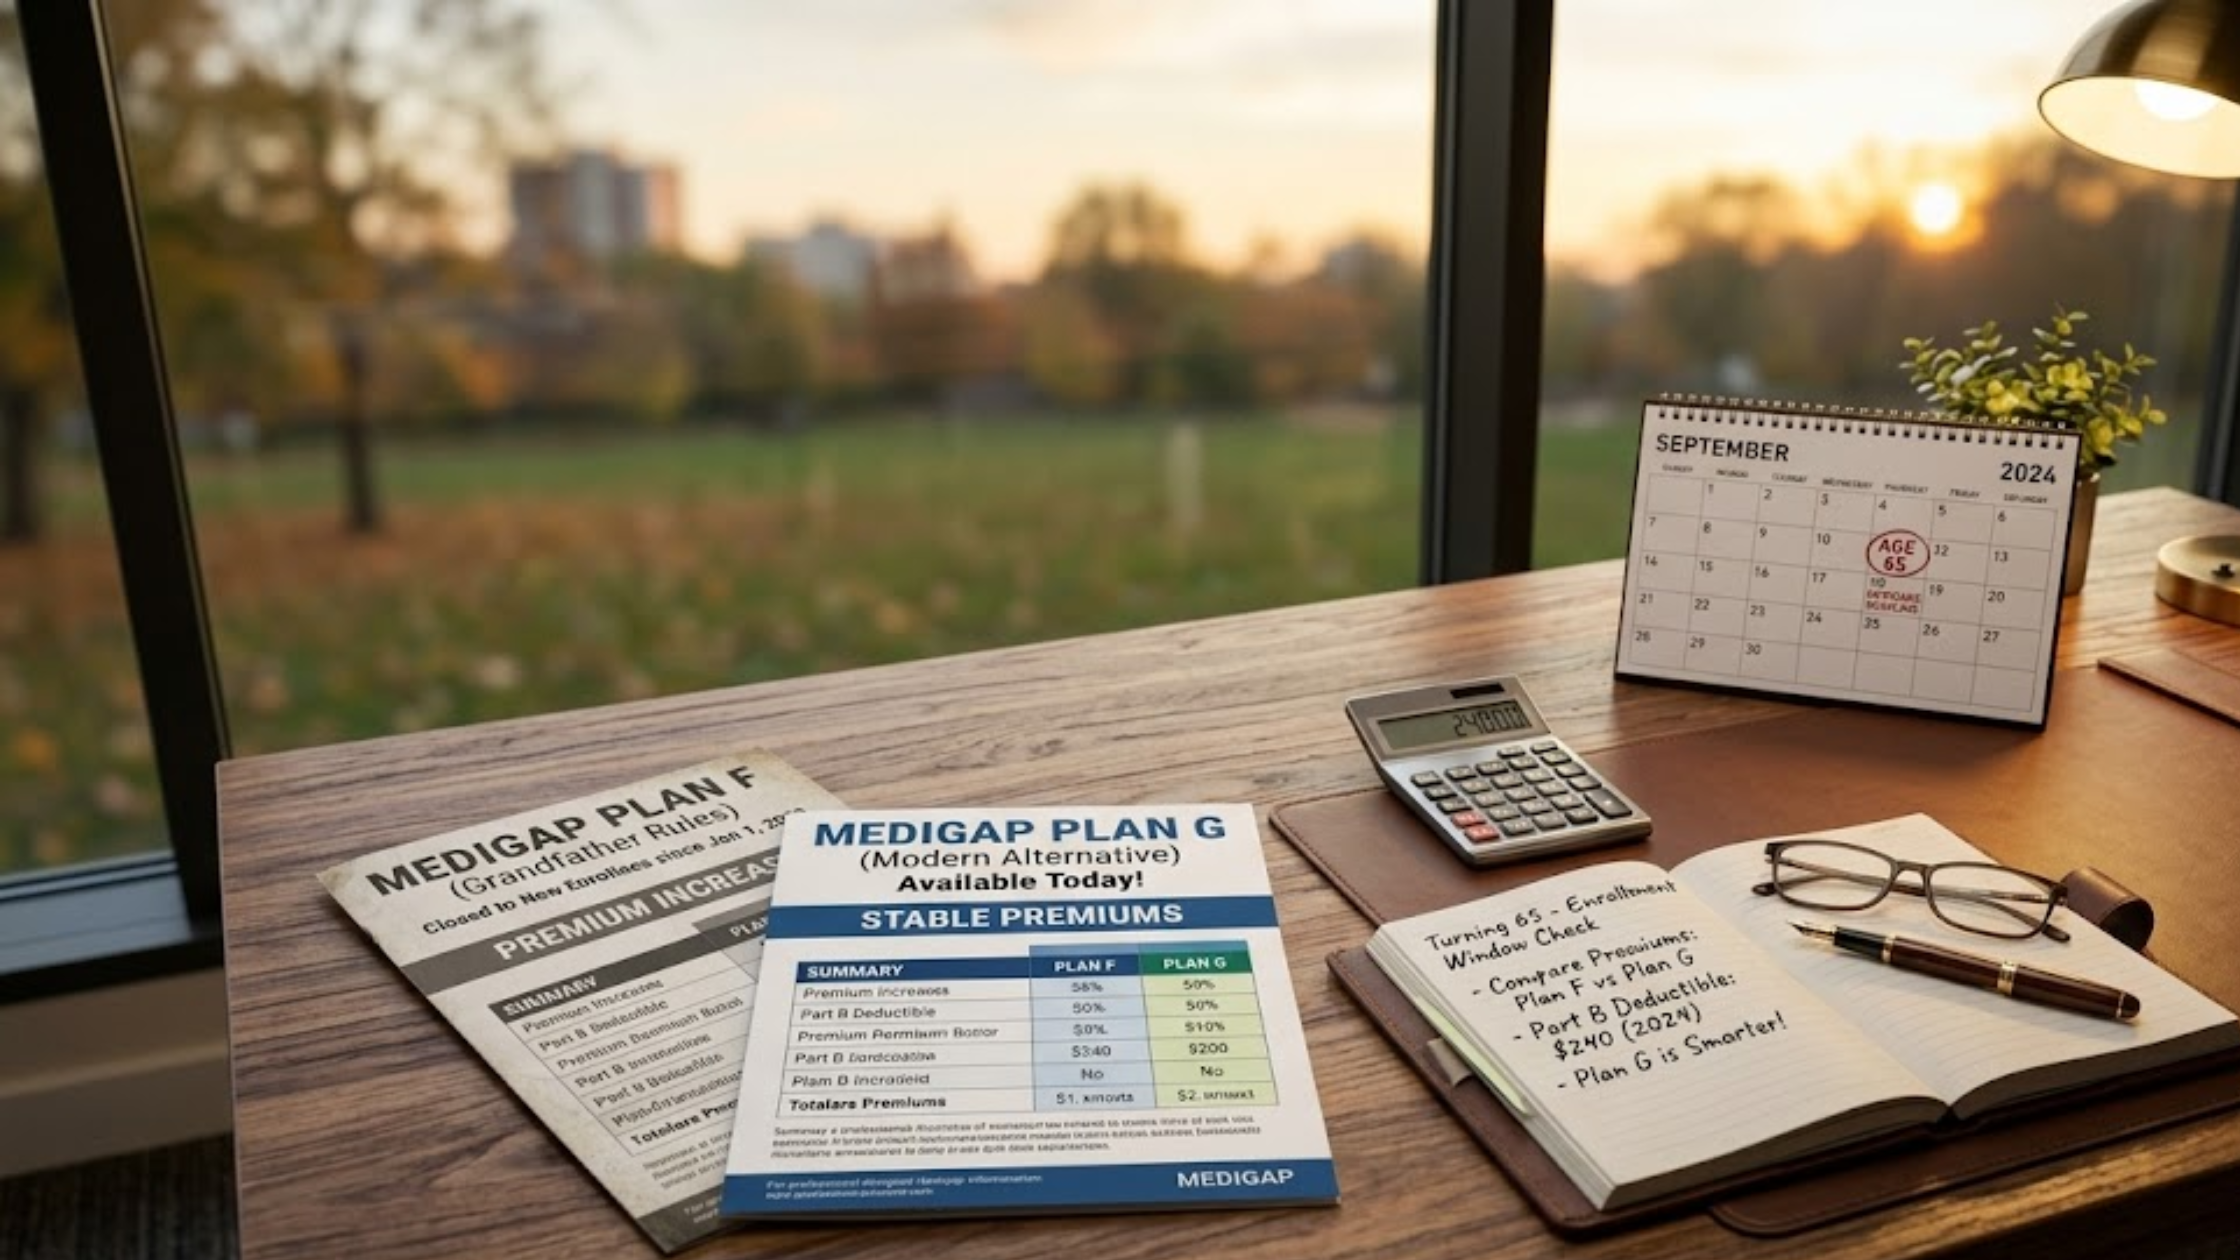
- Plan F Phase-Out: Anyone turning 65 after January 1, 2020, is legally barred from enrolling in Medigap Plan F.
- Plan G Alternative: Plan G offers identical coverage to Plan F except for the small annual Part B deductible.
- Cost Effectiveness: Choosing Plan G saves you money long-term because its stable premiums easily offset the deductible.
Turning 65 brings a flood of important healthcare decisions that require careful consideration. Older relatives and neighbors often insist that Medigap Plan F is the absolute best choice for supplemental coverage. They tell stories of never paying a single dime at the doctor or the hospital. Yet, conflicting news reports and broker advice constantly claim this famous plan no longer exists.
This conflicting information quickly makes an already overwhelming enrollment process feel totally impossible to navigate alone. The truth is that the landscape of supplemental coverage changed significantly a few years ago. If you reach eligibility age today, the available options look quite different than they did for older generations. We will explore exactly what happened to this renowned plan and outline the actual choices available moving forward. You will soon see that modern alternatives actually provide better long-term financial security for your retirement.
The 2020 Phase-Out: Why Medigap Plan F Disappeared
To understand why you cannot simply sign up for the plan your friends recommend, we must look back at recent legislation. Congress passed a federal law in 2015 to change how doctors receive payment and how patients share the cost of outpatient care. Part of this legislation aimed to make patients much more aware of their annual medical spending. Before this law took effect, Medigap Plan F covered every single gap in Original Medicare without question.
This comprehensive coverage included the annual Part B deductible. Because patients paid zero dollars out of pocket for doctor visits, lawmakers worried people overused standard medical services. To solve this perceived issue, the federal government created a strict new enrollment rule. Lawmakers barred anyone who became eligible for Medicare on or after January 1, 2020, from purchasing a policy that covers the Part B deductible.
Because Medigap Plan F covers that exact deductible, the government effectively phased it out for all new enrollees. If your 65th birthday is approaching now, you fall squarely into this new category of beneficiaries. Federal law prohibits insurance companies from selling you this specific policy today. This legal restriction is exactly why you keep hearing the plan is going away.
Grandfather Rules: Who Can Still Enroll?
You might still see television advertisements or receive mailers for Plan F. This happens solely because of specific grandfather rules built directly into the 2015 federal legislation. The 2020 cutoff date only applies to people who became eligible for Medicare after January 1, 2020. If someone turned 65 before that exact date, the government fully grandfathered them into the old system.
These grandfathered individuals can keep their current policies indefinitely without any penalty. They can even shop around and buy a brand new Medigap Plan F policy from a different insurance company today. Their older eligibility date legally secured their continued access to the plan forever. This loophole explains exactly why your older siblings or friends remain happily enrolled in it.
However, these grandfather rules absolutely do not apply to anyone turning 65 today. You cannot buy your way into this closed group of older beneficiaries. While this might sound frustrating at first glance, the exclusion acts as a massive blessing in disguise. Avoiding this older risk pool will likely save you a significant amount of money over the next decade.
The Modern Alternative: Introducing Medigap Plan G
Since federal law blocks you from purchasing the plan your friends have, you need a highly reliable modern alternative. Enter Medigap Plan G. The insurance industry considers this the new gold standard for supplemental coverage across the country. Providers specifically designed it to mirror the comprehensive coverage of the older policies while complying with the new federal laws.
If you want maximum peace of mind and the fewest surprise medical bills, Plan G delivers exactly what you need. The coverage provided by Plan G is virtually identical to Medigap Plan F. Both of these policies cover your expensive Part A hospital deductible completely. Additionally, they pay for your expensive hospital coinsurance during very long inpatient stays.
The coverage also extends to skilled nursing facility care and necessary hospice care. They both even cover Part B excess charges seamlessly. Excess charges occur when a doctor refuses the standard Medicare approved amount and bills you for an additional 15 percent. Both of these policies protect you completely from those unexpected extra fees (Medicare.gov).
The Only Difference Between the Two Plans
There is literally only one single difference between these two comprehensive options. Plan G simply does not pay the annual Part B deductible on your behalf. The Part B deductible is a very small, federally set amount that you pay once per year before your outpatient coverage begins. For 2024, the federal government set this amount at just $240 for the entire calendar year.
Once you pay that small deductible out of pocket, Plan G functions exactly like the plan your older friends have. It pays 100 percent of your remaining covered outpatient costs for the rest of the year. You never have to worry about frustrating copayments or complex coinsurance again. You simply pay that one small deductible and then enjoy total coverage for the remainder of the calendar year.
Why Plan G is a Smarter Financial Choice
You might initially feel cheated out of having your deductible covered completely. A closer look at the numbers shows why you should embrace the new system instead. When you examine the basic math, Medigap Plan G stands out as a smarter and much more cost-effective choice today. This advantage all comes down to how insurance companies calculate premiums and manage closed risk pools over time.
Because Medigap Plan F no longer accepts newly eligible 65-year-olds, the group of people inside that plan steadily grows older. The pool lacks healthy 65-year-olds entering the system to offset the rising healthcare costs of the older members. As a result, the insurance companies face significantly more claims for that specific older group. The companies must raise the monthly premiums for everyone remaining in that plan to maintain profitability.
These older premiums naturally rise at a much faster rate than other plans on the open market. Plan G actively takes in all the healthy, newly eligible 65-year-olds today. This constant influx of younger people keeps the risk pool incredibly stable and financially balanced. Because average claims remain lower, the monthly premiums for Plan G stay much more competitive and manageable.
When you compare the two policies side by side, the financial benefit becomes very clear. The difference in the annual premium cost between the two plans is almost always larger than the Part B deductible itself. For example, Plan F might cost $300 more per year in premiums than Plan G in your area. Since the Part B deductible only costs $240, choosing the older plan causes you to lose money. You essentially pay $60 extra a year just for the minor convenience of not writing a check to your doctor.
Common Questions About Your Supplemental Options
If you are still weighing your healthcare choices, you probably have a few lingering questions. Below are the most frequent concerns we address for adults approaching their 65th birthday.
-
Does Medigap Plan F still exist today? Yes, it still exists for people who reached Medicare eligibility before January 1, 2020. However, federal laws completely block anyone turning 65 today from purchasing it.
-
Will Plan G cover my unexpected hospital stays? Yes, Plan G fully covers your Part A hospital deductible and hospital coinsurance. You avoid facing large, unexpected bills for inpatient hospital care.
-
Do doctors accept Plan G as easily as they accept older plans? Yes. If a doctor accepts Original Medicare patients, they must accept any standardized Medigap policy, regardless of the assigned letter. Your access to top doctors and specialists remains completely unchanged.
-
Can I ever switch from a Medicare Advantage plan to Plan F? If you reached Medicare eligibility after January 1, 2020, you can never switch into Plan F under any circumstances. You must look at modern alternatives like Plan G when returning to Original Medicare.
Planning Your Enrollment Strategy Carefully
Now that you know the truth about Medigap Plan F, you can move forward with absolute confidence. You do not need to worry about missing out on a discontinued policy. The market offers a highly effective, comprehensive option available to you right now. The secret to success involves enrolling at the exact right time to protect your health and your wallet.
Your Open Enrollment Period serves as a strict six-month window of opportunity. It begins the very first month you turn 65 and hold active Part B coverage. During this exact window, insurance companies cannot deny you coverage based on any pre-existing medical conditions. They must sell you a policy at the best available preferred rate without asking any health questions (Medicare.gov).
If you miss this vital enrollment window, you face medical underwriting questions later. The insurance company gains the legal right to deny your application entirely if you develop a serious health condition. This critical deadline requires careful, proactive planning to ensure long-term coverage. You want your policy selected and your paperwork submitted long before this protective window permanently closes.
Next Steps for a Stress-Free Retirement
Navigating these complex healthcare rules alone often feels quite daunting. The transition into this new phase of life should feel exciting and liberating, not intensely stressful. If you want to guarantee you choose the right coverage and hit all your specific deadlines, expert help makes all the difference.
Anyone looking to enroll into Medicare for the first time can rely on The Medicare Coach. Our Medicare Enrollment Concierge services guide you step by step through the modern alternatives and guarantee a completely smooth transition. We handle the confusing paperwork so you can focus completely on enjoying your retirement years. Are you ready to find the perfect supplemental coverage for your unique needs?
Continue Learning About Medicare
- Choosing the Best Medigap Plans for Your Needs
- What is Medigap: Understanding Supplement Plans
- Medigap Plan Comparison: Making the Right Choice
